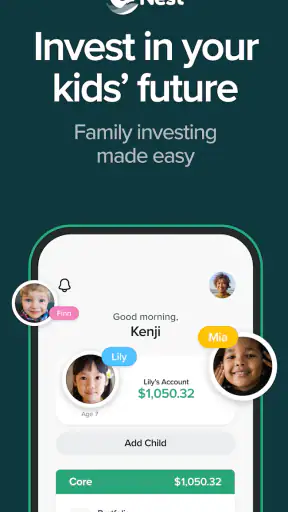
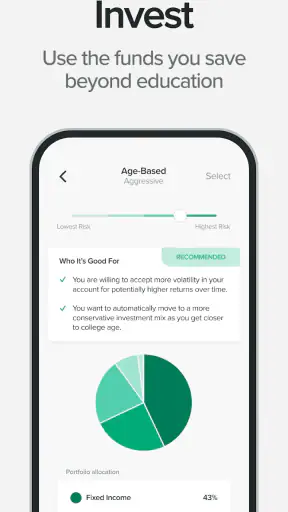
I approached UNest: Invest & Save for Kids as a finance app for parents who want to make investing for a child part of ordinary family planning rather than a once-a-year task. Its focus is a UTMA custodial account, so the central idea is straightforward: an adult sets money aside and invests it for a child’s future. That makes it quite different from a budgeting app that only tracks spending or a standard savings app that leaves money in cash.
My overall impression is that UNest is easiest to appreciate when you want a guided starting point. It is free to install, aimed at Everyone, and developed by UNest Holdings, Inc. The app has passed the early-adopter stage, with more than one hundred thousand installs and an average rating of 3.8 from roughly two and a half thousand ratings. Those figures suggest a real user base, but they also tell me to keep expectations measured: this is a practical investing tool, not a universally loved, friction-free replacement for every financial service.
How UNest feels in everyday use
The first thing I noticed about an app like this is that its value depends less on constant interaction and more on how clearly it helps me make a long-term decision. I would not open it repeatedly throughout the day like a banking app. Instead, I would use it when deciding how much to contribute, checking the child’s account, or reviewing whether the plan still fits the family budget.
That limited-use pattern is important for performance expectations. A finance app built around a custodial account does not need to feel like a high-speed social feed. What matters more is whether screens open without confusion, account information is presented clearly, and routine actions do not feel unnecessarily complicated. In my experience, the strongest reason to choose UNest is the way it puts the child-focused purpose at the center rather than making me assemble that purpose from several unrelated tools.
The app runs on Android devices using at least Android 7.0, which covers a broad range of phones and tablets. I would still separate compatibility from comfort. A device may meet the operating-system requirement yet feel slow if it has limited memory, an aging processor, or very little free storage. The app itself belongs to finance, so I would expect relatively modest resource demands during normal use, but I would not treat an older phone as automatically ideal for sensitive account management.
UNest is currently listed as version 3.8.1. Seeing a current version number is useful because it indicates that the app is maintained as an active product rather than abandoned software. It does not guarantee that every screen will feel equally polished on every device, so I would keep the operating system updated where possible and avoid judging the service solely by how quickly an older handset launches it.
What the custodial account changes
The UTMA structure is the detail a prospective user should understand before thinking about design or speed. This is not simply a personal investment dashboard with a child-themed label. Money placed in a custodial account is intended for the child’s benefit, and that creates a different kind of responsibility from putting money into an ordinary personal savings goal.
For me, that makes UNest more suitable for a deliberate family plan than for casual experimentation. Before contributing, I would decide whether the account’s purpose matches the child’s likely future needs and whether I am comfortable with the responsibilities attached to custodial investing. A parent who only wants to save for a short-term purchase may find a conventional savings account easier to understand and manage.
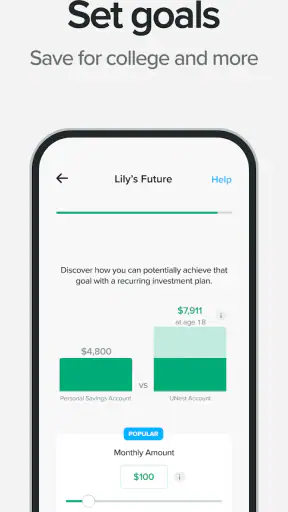
The app’s child-centered design can also help with motivation. Instead of treating investing as an abstract personal finance exercise, I can connect contributions to a recognizable goal: education, a first car, training, or another future milestone. That emotional connection is useful, but it should not replace checking the practical details of the account and the investment approach.
A realistic family routine
Imagine a parent who receives income twice a month and wants to put a manageable amount toward a child’s future. Rather than waiting until the end of the year and trying to remember what was affordable, that parent could use UNest as the dedicated place to review the custodial account and make contributions part of the household routine. The useful workflow is not complicated: open the app when the budget is known, confirm that the planned amount still works, and then leave the long-term investment to do its job rather than constantly reacting to daily market noise.
I like this scenario because it shows where the app can be genuinely helpful. The challenge for many families is not understanding that investing exists; it is turning good intentions into a repeatable habit. A dedicated child account creates a visible boundary between money for the child and money for current household spending.
There is also a trade-off. A separate account can make the goal clearer, but it can make the overall financial picture feel more fragmented if the family already uses several banking and investment services. I would keep a simple external record of the contribution plan, especially if more than one adult is involved. That is not a criticism of UNest specifically; it is a sensible way to prevent a child-focused account from disappearing into a collection of disconnected financial apps.
Speed during routine actions
For normal use, I would judge UNest by the speed of practical tasks rather than by flashy transitions. Opening an account overview, checking the latest information, and moving through contribution-related screens should feel direct. If a finance app makes me search for basic information, the delay is not only technical; it increases the chance that I postpone an important task.
UNest’s purpose suggests a relatively focused workload. It is not designed for editing videos, streaming media, or processing large files, so I would not expect it to place heavy demands on the phone during a short session. A modern device should be the best environment for quick checks, while an older device may take longer to launch or switch between screens. That distinction matters if a user is deciding whether a sluggish experience comes from the app or from the handset.
Network quality will naturally affect any account-based finance app. A weak connection can make current information take longer to appear, and I would avoid repeatedly tapping buttons when a screen seems to be waiting. With financial actions, patience is safer than assuming a delayed response means nothing happened. I would first check whether the screen updates, then review the account activity before trying again.
That is one of my more important practical tips: do not treat a slow confirmation screen like a frozen game level. Repeating an action without checking its status can create unnecessary uncertainty. A calm, single-action workflow is better suited to UNest than opening it while rushing between other tasks.
Heavier moments and resource demands
The app’s heaviest moments are likely to occur when it is loading account information, handling secure sign-in steps, or displaying updated investment details rather than when it is sitting open on the phone. I would expect those moments to be more sensitive to internet quality and device age than a simple static screen.
For most users, I would expect battery use to be modest because this is a focused finance tool rather than an app built around continuous media playback, navigation, or background entertainment. Still, I would not leave any finance app open unnecessarily. Closing it after completing a task is a sensible habit, particularly on a phone that already struggles with many open apps.
Storage pressure can also affect the overall experience. The app may not be resource-heavy in the way a large game is, but a phone with nearly full storage can behave poorly across the board. If UNest starts slowly while other apps are also stalling, freeing space and restarting the device may be more useful than immediately assuming the account service is unreliable.
One non-obvious trade-off is that a deliberately calm investing workflow can feel less responsive than a conventional banking app that is built around instant balances and frequent transactions. That does not automatically mean UNest is performing badly. The app is tied to a longer-term investing purpose, so a user should value clarity and correct status information over the feeling of constant activity.
Stability and recovering from interruptions
Reliability matters more here than visual polish. When I use a finance app, I want confidence that an interruption will not leave me guessing about whether a contribution or account change went through. The safest approach with UNest is to treat every important action as something to verify afterward rather than something to repeat immediately.
If the app closes, the connection drops, or the phone switches to another task, I would reopen it and review the account status before attempting the same action again. This recovery habit is especially useful on older Android hardware, where memory management may close apps in the background. It also protects against the common mistake of confusing an incomplete display with an incomplete transaction.
I would use the app when I have enough time to read each confirmation and check the resulting information. That may sound obvious, but families often manage finances in short gaps between work, school, and errands. UNest can fit into a busy routine, yet the financial nature of the task means rushing is a poor way to test its reliability.
The rating of 3.8, alongside around four hundred and thirty written reviews, gives me a balanced signal rather than a reason for either alarm or blind confidence. There is enough activity to show that people are using and evaluating it, but the score is not so high that I would assume every user finds the experience seamless. I would install it, complete the setup carefully, and decide whether its workflow feels dependable on my particular phone before making it central to my family’s financial routine.
Device constraints and practical preparation
Because Android 7.0 is the minimum operating system, users with older phones should check that their device is supported before planning around the app. Meeting the minimum is only the starting point. For a smoother experience, I would keep the phone’s system software current, close demanding apps before opening UNest, and make sure there is enough free storage for normal updates.
Screen size can affect comfort too. A small phone may be perfectly usable for checking an account, but financial figures and explanatory text deserve careful reading. I would avoid making important decisions while using a cracked screen, extreme display scaling, or a device with touch problems. Those are simple physical constraints, yet they can turn a clear financial workflow into a source of mistakes.
Shared devices deserve special attention. If a child also uses the phone, I would not leave the finance app open or rely on the device being private. A custodial account is connected to a child, but that does not mean the child should have unrestricted access to the adult’s financial session. Locking the phone and closing the app after use are basic precautions.
I would also think about notifications and attention. A child’s investment account is a long-term project, so constant checking can encourage emotional reactions to short-term changes. The better use of UNest is as a scheduled checkpoint: review the plan when the household budget changes, when a contribution needs adjusting, or when you are intentionally checking progress.
Costs, expectations, and alternatives
The app is free to download, but it includes in-app purchases ranging from about five dollars to around one hundred and fifty dollars per item. That makes it important to distinguish the download price from the total cost of using the service. Before committing money, I would read the purchase and account terms carefully and make sure I understand which charges apply to the particular action or service I intend to use.
This is also where UNest should be compared with ordinary alternatives. A bank savings account may be easier for a short-term goal because the balance is straightforward and the experience is familiar. A general brokerage account may offer more control for an experienced investor, but it can require more decisions and may not provide the same child-focused structure. A family budgeting app can help plan contributions, yet it does not replace the custodial account itself.
UNest makes the most sense when guidance and a dedicated child goal are more valuable to me than maximum control. I would be less enthusiastic about it if I already manage a sophisticated investment setup and want detailed control over every holding, tax decision, or account feature. In that case, a broader brokerage service may fit better, provided I am prepared to handle the extra complexity myself.
The in-app purchase range also means I would not judge the service solely by the word “free.” Free access can be a convenient way to explore the workflow, but the real decision is whether the ongoing arrangement, account structure, and available tools suit my family. I would compare those terms with a bank or brokerage option before transferring a meaningful amount.
Who should use it, and who should skip it
I see UNest as a good fit for a parent or guardian who wants one clearly defined place for investing on behalf of a child, prefers a guided experience, and is willing to treat the account as a long-term commitment. It may also suit someone who has struggled to turn general saving intentions into a repeatable family habit.
I would skip it for a user who only needs an emergency fund, a near-term purchase fund, or a simple cash account. Investing introduces a different level of uncertainty and responsibility, so a conventional savings product may be more appropriate for money that must remain stable and immediately available.
I would also look elsewhere if the main priority is advanced investment control. UNest’s appeal is its focused child-saving purpose, not the promise of being an all-purpose financial workstation. Experienced investors may prefer a service that exposes more choices, even if that means doing more research and managing the account with less guidance.
Another important question is whether the account structure matches the family’s expectations. A child-focused custodial account should not be treated as a casual label placed on money that the adult might later redirect freely. I would learn how the arrangement fits my responsibilities before contributing, and I would discuss the plan with any other adult who may be involved in the child’s finances.
My performance verdict
After weighing the likely workload, device requirements, recovery habits, and financial purpose, I see UNest as a focused tool rather than a high-frequency finance dashboard. Its performance should be judged by dependable access to the child’s investment account and a clear contribution workflow, not by how many screens or advanced controls it offers.
The app’s strongest practical advantage is concentration: it gives a family a dedicated place to think about investing for a child. That can make a vague goal more actionable. Its main friction is that the custodial structure and possible in-app costs deserve careful attention, while users seeking instant cash access or advanced portfolio control may be better served elsewhere.
For my own recommendation, I would tell a friend to try UNest if the goal is long-term child investing and the guided, focused approach sounds more useful than a general brokerage account. I would install it on a reasonably current Android device, use it during unhurried budget reviews, verify every important action after interruptions, and compare the complete costs with familiar alternatives before committing. With those expectations, it feels like a sensible starting point for building a child-focused investment habit, rather than a universal answer to every family finance need.


